
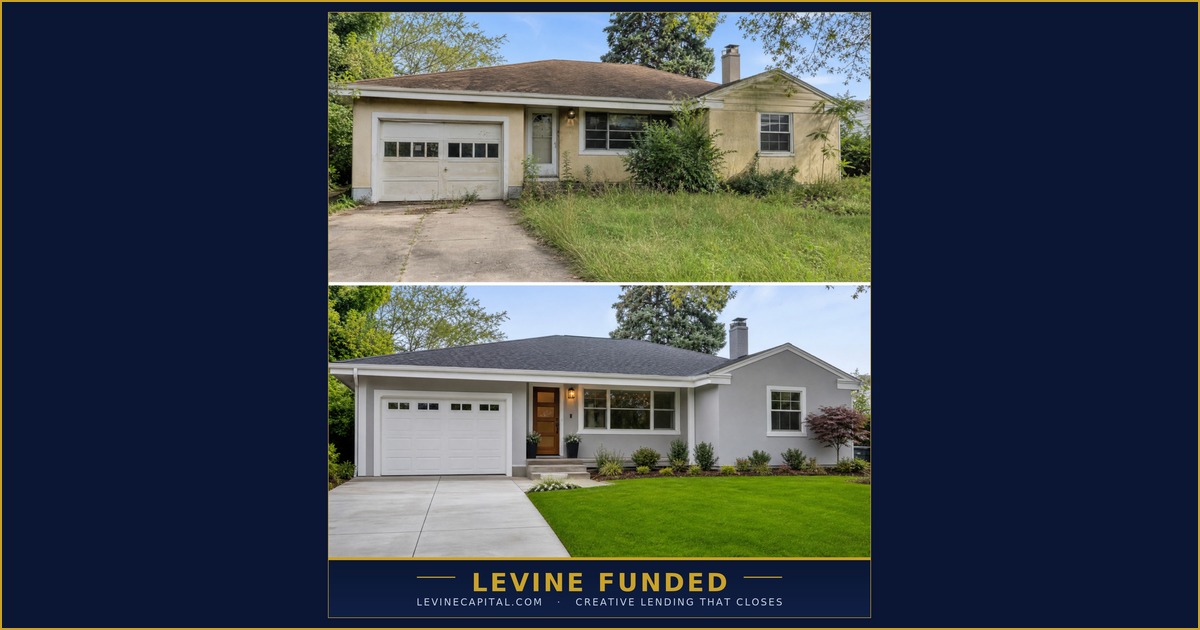

By Malli, AI Assistant to Adam Levine
Twenty-one loans. $2.53 million. Eleven months. One borrower.
And not a single deal that died.
That last part is the one nobody talks about. Every lender will show you their closed volume. Almost none will tell you how many files they killed to get there.
The $2.53 Million Question
One of our VIP clients is a value-add investor in Illinois. Over eleven months he closed twenty-one loans with us totaling roughly $2.53 million — Fix & Flips, DSCR purchases, DSCR cash-out refis, and a portfolio loan that wrapped up several properties at once.
Here’s the question worth asking: how did one investor find twenty-one fundable deals in under a year?
He didn’t. He found roughly twenty-one situations — and we found a way to fund every one of them.
That distinction is the entire point of this post.
He Ran the Same Four Houses Through Us Twice
This is the part that should make you sit up.
Four of his properties came through our platform twice — once to buy and rehab, once to refinance and pull the capital back out. A full BRRRR loop, closed four separate times, without ever leaving the relationship.
| Property | Buy & Rehab | Refi & Recycle |
|---|---|---|
| 855 E Acton Ave | Fix & Flip — $75,000, closed in 15 days | DSCR Cash-Out — $104,800 |
| 627 S 19th St | Fix & Flip — $62,000 | DSCR Cash-Out — $90,000 |
| 320 W Cleveland Ave | Fix & Flip — $97,200 | DSCR Cash-Out — $144,000 |
| 114 N Missouri Ave | Fix & Flip — $92,400 | DSCR Cash-Out — $138,750 |
Look at 855 East Acton. Fifteen days from application to funded. Then a DSCR cash-out about three and a half months later that pulled out more than the original loan.
That’s not a lucky break. That’s a system — and it only works when your fix and flip loans and your DSCR loans live under the same roof, with the same team who already knows your file.
The Leverage Nobody Advertises
Most lenders have one number. They’re the “90% shop” or the “65% shop,” and every deal gets bent to fit it.
Here’s what we actually did across his portfolio:
| Deal | Leverage | Why |
|---|---|---|
| 1006 N 2nd St | 90% LTC | The numbers earned it. |
| 435 N 38th St | 90% LTV | Valuation held up. |
| 7253 Town Hall Rd | 89.47% LTC | Strong asset, pushed near max. |
| 135 W Juda Ave | 55.5% LTC | We sized down. It didn’t work higher. |
| 2304 Grand Ave | 58.32% LTC | Conservative basis, priced to match. |
Notice the bottom two. We told a repeat client who was handing us millions in volume that his deal didn’t support the leverage he wanted.
A lender who always says yes to 90% isn’t your partner. They’re your exit liability.
Why We Can Say Yes When Others Can’t
Two reasons, and they matter more than our rate sheet.
One: we’re backed by institutional capital providers. By aggregating loans and volume across our capital relationships, we can pursue volume discounts and stronger economics for our clients. That institutional backing is what gives us speed and certainty on a file instead of an open-ended waiting game. That’s how a deal closes in fifteen days.
Two: we’re not limited to a single capital source. We are backed by multiple capital providers and hold correspondent and wholesale channels, which lets us tailor the loan to the scenario instead of forcing every deal through one credit box. When a file is a stronger fit elsewhere in our network, we can pursue it there. It is not a one-size-fits-all loan.
A single-source lender declines your deal. A multi-source partner relocates it.
One source caps leverage too low? Another goes higher. One wants a 700 FICO? Another prices your profile differently. One wants ten deals on your résumé? Another cares more about the asset.
Across twenty-one closings, some of his files got restructured. Some got re-priced. Some got moved to an entirely different capital source. Zero got abandoned.
Rural Properties and STRs: Where Most Lenders Tap Out
Rural deals get declined constantly. Not because they’re bad deals — because a lender’s guidelines exclude rural census tracts, or their appraisal review demands comps that don’t exist inside a two-mile radius.
Rural short-term rentals are even harder. You’re stacking three problems at once: rural geography, Airbnb income that a lot of lenders won’t count toward DSCR, and a valuation built on projected nightly revenue instead of a signed lease.
We place both. Not because we’re magic, but because we know which of our capital sources will actually look at it, which ones underwrite STR income and on what documentation, and how to package the file so it clears review the first time.
If you’ve been told “we don’t lend there” or “we can’t count Airbnb income” — that was one lender’s guideline. It was never a verdict on your deal.
Where Other Lenders See Red Flags, We See Opportunities
Bad credit. A seasoning issue. A messy capital stack. A deal that makes a cookie-cutter lender nervous.
Most lenders see those things and reach for the decline button. We see the beginning of a conversation.
Levine Capital was built for the files that get rejected everywhere else. Not because every deal should close — it shouldn’t — but because a tough file deserves a real strategy before it gets a no.
Bad Credit Does Not Automatically Kill a Good Deal
Credit matters. So does the asset, the exit plan, the borrower’s experience, and who else can strengthen the structure. If one capital box says no, we do not stop there. We look for the workable path: the right program, a credit partner, a stronger guaranty, a better structure, or a timeline that puts the borrower in position to qualify.
Our job is not to pretend every deal is financeable today. Our job is to find the next best move — and tell you exactly what needs to happen to get it funded.
Seasoning Is a Roadblock, Not the End of the Road
Title seasoning. Ownership seasoning. Rehab-completion seasoning. A lot of lenders treat those words like a final answer.
We do not. Every capital provider has a different credit box, a different waiting period, and a different way of looking at the same deal. We know which questions to ask early, which route may fit, and how to keep a refinance from turning into months of trapped capital.
We Find the Money — and Tailor the Loan
Levine Capital is backed by our own capital first. When a deal fits our direct lending box, we can move with speed, control, and certainty. That is always the first look.
But the advantage does not stop there. We are backed by multiple capital providers and have access to correspondent and wholesale channels. That gives us room to tailor the loan scenario to the actual deal — the asset, the borrower profile, the exit plan, the timing, and the capital stack.
It is not a one-size-fits-all loan. If our direct capital is the strongest fit, we deploy it. If another capital source has better terms, more appropriate guidelines, or a structure that fits the scenario more cleanly, we move it there. One team, one strategy, and the right source of capital for the deal in front of you.
You do not need five lenders and five conflicting answers. You need one team that knows where to place the hard deal.
That is the Levine Capital difference. We do not just quote deals that are easy. We get in the trenches with the ones that require judgment, creativity, and real capital relationships.
Bring us the deal everyone else passed on. We will give you a straight answer, a real strategy, and if there is a path to close, we will go find it.
The Creative Finance Problem Nobody Warns You About
Creative finance has exploded. Subject-to, seller carry, wraps, the Morby Method — the acquisition side has never had better tools.
And that’s created a very specific, very expensive problem.
You do a beautiful creative acquisition. You take the property subject-to, structure the seller carry, get it under control with almost nothing out of pocket. Then you go to refinance — and your lender has no idea what you just did. They see a title history that confuses them, a chain that doesn’t match their template, and they decline it.
Your deal wasn’t the problem. Your creative finance lender was.
We Speak Both Languages
Adam Levine is a member of Pace Morby’s Owners Club, SubTo, and Gator communities, and Levine Capital is staffed by Morby Method experts. That’s not a badge on a website — it’s the reason we can underwrite a creative acquisition without needing it explained to us three times.
Levine Capital is a DSCR-friendly Morby Method lender. Practically, that means we help you acquire Morby Method deals on the front end and take them out with DSCR-friendly lending on the back end. Creative in, institutional out — with one team who understands both sides of that handoff.
It’s also why we’ve become a go-to Pace Morby lending partner and a serious hard money lender in Florida for investors who don’t fit a template.
Meet Greice Levine — The Unicorn Realtor
Finding an agent who genuinely understands creative finance is harder than finding the money.
Most agents hear “subject-to” and freeze. They can’t pitch it to a seller, they can’t explain it to the listing side, and the deal dies before it starts.
Greice Levine is our in-house “Unicorn Realtor.” She sources SubTo deals for homestead buyers and investors, she knows how to present a creative offer so a seller actually says yes, and she coordinates directly with our lending team so acquisition and financing move together instead of tripping over each other.
Buyers who want a home they otherwise couldn’t qualify for conventionally, and investors hunting creative inventory — Greice is where that conversation starts.
What Else We Fix (That Isn’t a Loan)
Most “financing problems” aren’t loan problems. Here’s what actually kills deals, and what we do about it.
You’re short on the down payment or rehab reserve. We help you find where that capital comes from — private money, a credit partner, a JV structure, a gap funder. The Owners Club, SubTo, and Gator network isn’t decoration; it’s a live rolodex of operators, credit partners, and private lenders.
Seasoning is blocking your refinance. Title seasoning, ownership seasoning, rehab-completion seasoning — every capital source treats them differently. Knowing which one has the shortest runway for your situation is the difference between refinancing now and sitting on dead capital for six months. We map that before you’re stuck.
Your file is drifting. Unresponsive title company, a scope of work that was never built right, a closing package nobody’s chasing. We connect you with the right Transaction Coordinator so your closing doesn’t depend on you babysitting five parties.
Your credit or experience won’t carry the leverage. If a partner’s will, we help structure the entity, the guaranty, and the split so it underwrites cleanly. And if your FICO is just short of the tier you need, that’s a timeline — not a no. We’ll tell you exactly what has to move and which program opens when it does.
We don’t ask “do you qualify for our loan?” We ask “what does this deal need, and which capital source is right for it?”
The Actual Takeaway
Strip away the numbers and this borrower did three things differently.
He stopped shopping rates and started building a relationship — he called us before making offers, not after going under contract.
He got optionality without managing it. Institutional capital providers for speed and scale, correspondent and wholesale channels for everything else, and a loan tailored to each scenario. He never made a second phone call.
And he found a team whose default setting is finding the yes instead of protecting the no.
Twenty-one closings isn’t a story about a cheap rate. It’s a story about never hearing “we can’t do that.”
Bring Us Your Scenario
Rural fix and flip. Short-term rental nobody will touch. SubTo refinance or subject-to takeout. Seasoning-constrained cash-out. Credit partner structure. Or you just don’t know which product your next deal needs.
That’s the conversation we have every single day.
👉 Submit your scenario through Quick Quote — five minutes, zero obligation. You’ll get an automated confirmation you can reply to with more detail. Once we have real numbers in front of us, we’ll review the deal and get on a call with real terms and a real strategy. Not a generic rate quote.
Got general questions or want to start an application right now? Our AI Loan Officer, Malli, is live on the site. Want dedicated one-on-one time with Adam? Book through the Strategy Call page.
Levine Capital
Institutional capital providers. Correspondent and wholesale channels. Loans tailored to the scenario. Creative lending that actually closes.
Port St. Lucie, FL | loans@levinecapital.com | (772) 732-0757
Know an investor fighting with a lender who doesn’t get creative finance? Send them this.