

By Malli, AI Assistant to Adam Levine
A real estate investor can do many things right and still reach the refinance stage with a credit problem. Renovation costs may have exceeded the original budget. Materials, contractors, insurance, utilities, and carrying costs may have gone onto personal credit cards. Credit utilization rises, the investor’s FICO score falls, and the long-term lender that looked like a fit at the beginning may no longer approve the exit.
A fix-and-flip investor can face an even more urgent version of the same problem. The project is not complete, the current loan is approaching maturity or already in default, and the existing lender will not provide additional time or construction funds. The investor needs a payoff, money to finish the property, or both.
Levine Capital can evaluate both situations. Depending on the property, project status, cash flow, borrower profile, and available equity, a qualified investor may have access to a DSCR loan program with a minimum FICO score as low as 550 or a mid-construction bailout refinance that replaces the existing bridge lender and may provide funds to complete the work.
A lower credit score or a stalled renovation does not automatically mean the deal is over. It means the financing must be matched to the property’s current condition and the investor’s realistic exit strategy.
Request a Levine Capital Quick Quote for a confidential review of your property, payoff, project status, and exit strategy.
Why Credit Often Drops at the Worst Point in a BRRRR Project
The BRRRR strategy—buy, rehab, rent, refinance, repeat—depends on a successful transition from short-term acquisition or renovation financing into long-term rental financing. That transition can become difficult when an investor carries project expenses on personal revolving credit.
Even when payments are made on time, heavy credit-card utilization can reduce a borrower’s score. The investor may have completed the renovation, leased the property, and created a cash-flowing asset, yet still fall outside the credit requirements of the original refinance plan.
This creates a frustrating mismatch: the property may be performing, but the borrower’s personal credit profile has temporarily weakened. A low-FICO DSCR option may provide another path because the property’s rental income and proposed debt obligation are central to the analysis, although credit, reserves, appraisal, property eligibility, and the complete borrower file still matter.
Potential Financing Paths by Investor Situation
- If the renovation is complete and the property is rented or ready to rent, a low-FICO DSCR refinance may replace short-term debt with rental financing.
- If the credit score fell after renovation expenses were charged to personal cards, a DSCR program accepting FICO scores as low as 550 may evaluate the property’s cash flow despite the weaker credit profile.
- If the project is unfinished and the bridge loan is maturing or in default, a mid-construction bailout refinance may pay off the existing lender and create a workable completion plan.
- If the property needs additional renovation funds before it can stabilize, a new bridge or construction-completion loan may fund eligible remaining work, subject to underwriting.
- If the investor plans to hold the property after completion, a bridge-to-DSCR strategy may complete the project first and then transition it to long-term rental debt.
What Is a Low-FICO DSCR Loan?
A Debt Service Coverage Ratio loan, commonly called a DSCR loan, is a business-purpose real estate loan generally underwritten around the investment property’s ability to support its proposed debt payment. Instead of relying primarily on personal income documents, the lender evaluates qualifying rental income, housing expenses, property value, borrower credit, liquidity, reserves, and other program requirements.
For borrowers whose credit weakened during a project, Levine Capital has access to a DSCR loan product with a minimum qualifying credit score as low as 550. This can be valuable for investors who have a viable rental property but no longer meet the higher credit threshold anticipated when the project began.
Explore Levine Capital’s DSCR rental loan options for long-term investment-property financing.
The 550 minimum is not a blanket approval standard. Pricing, leverage, required reserves, prepayment terms, eligible property types, loan purpose, geographic availability, and documentation requirements vary by scenario and capital provider. Lower credit may also result in more conservative leverage or different terms.
Trapped in a Fix-and-Flip Loan? A Bailout Refinance May Offer a New Start
An unfinished project normally cannot move directly into permanent DSCR financing because the property may not yet be rent-ready or able to demonstrate sufficient qualifying income. In that situation, the immediate need is usually a mid-construction refinance, sometimes described as a fix-and-flip bailout loan or construction-completion loan.
Learn more about Levine Capital’s fix-and-flip financing options for acquisition, renovation, and bridge scenarios.
A properly structured bailout refinance may accomplish several goals. It may pay off the current lender, including an eligible matured or defaulted bridge loan. It may establish a new loan term and updated project plan. It may provide additional construction proceeds for eligible remaining work when supported by the budget, value, equity, and underwriting. It may also create a defined path to sale or to a later DSCR refinance once the property is complete and stabilized.
Default creates urgency, but it does not automatically eliminate every option. A lender will need to understand why the project stalled, how much work remains, what has already been invested, the property’s current and projected value, the payoff amount, and whether the revised plan is achievable.
The earlier the investor requests a review, the more room there may be to structure an orderly payoff and completion strategy. Waiting until a foreclosure deadline or another critical date can sharply reduce available choices.
A Recent Levine Capital Closing: Pivoting After the Borrower’s Credit Dropped
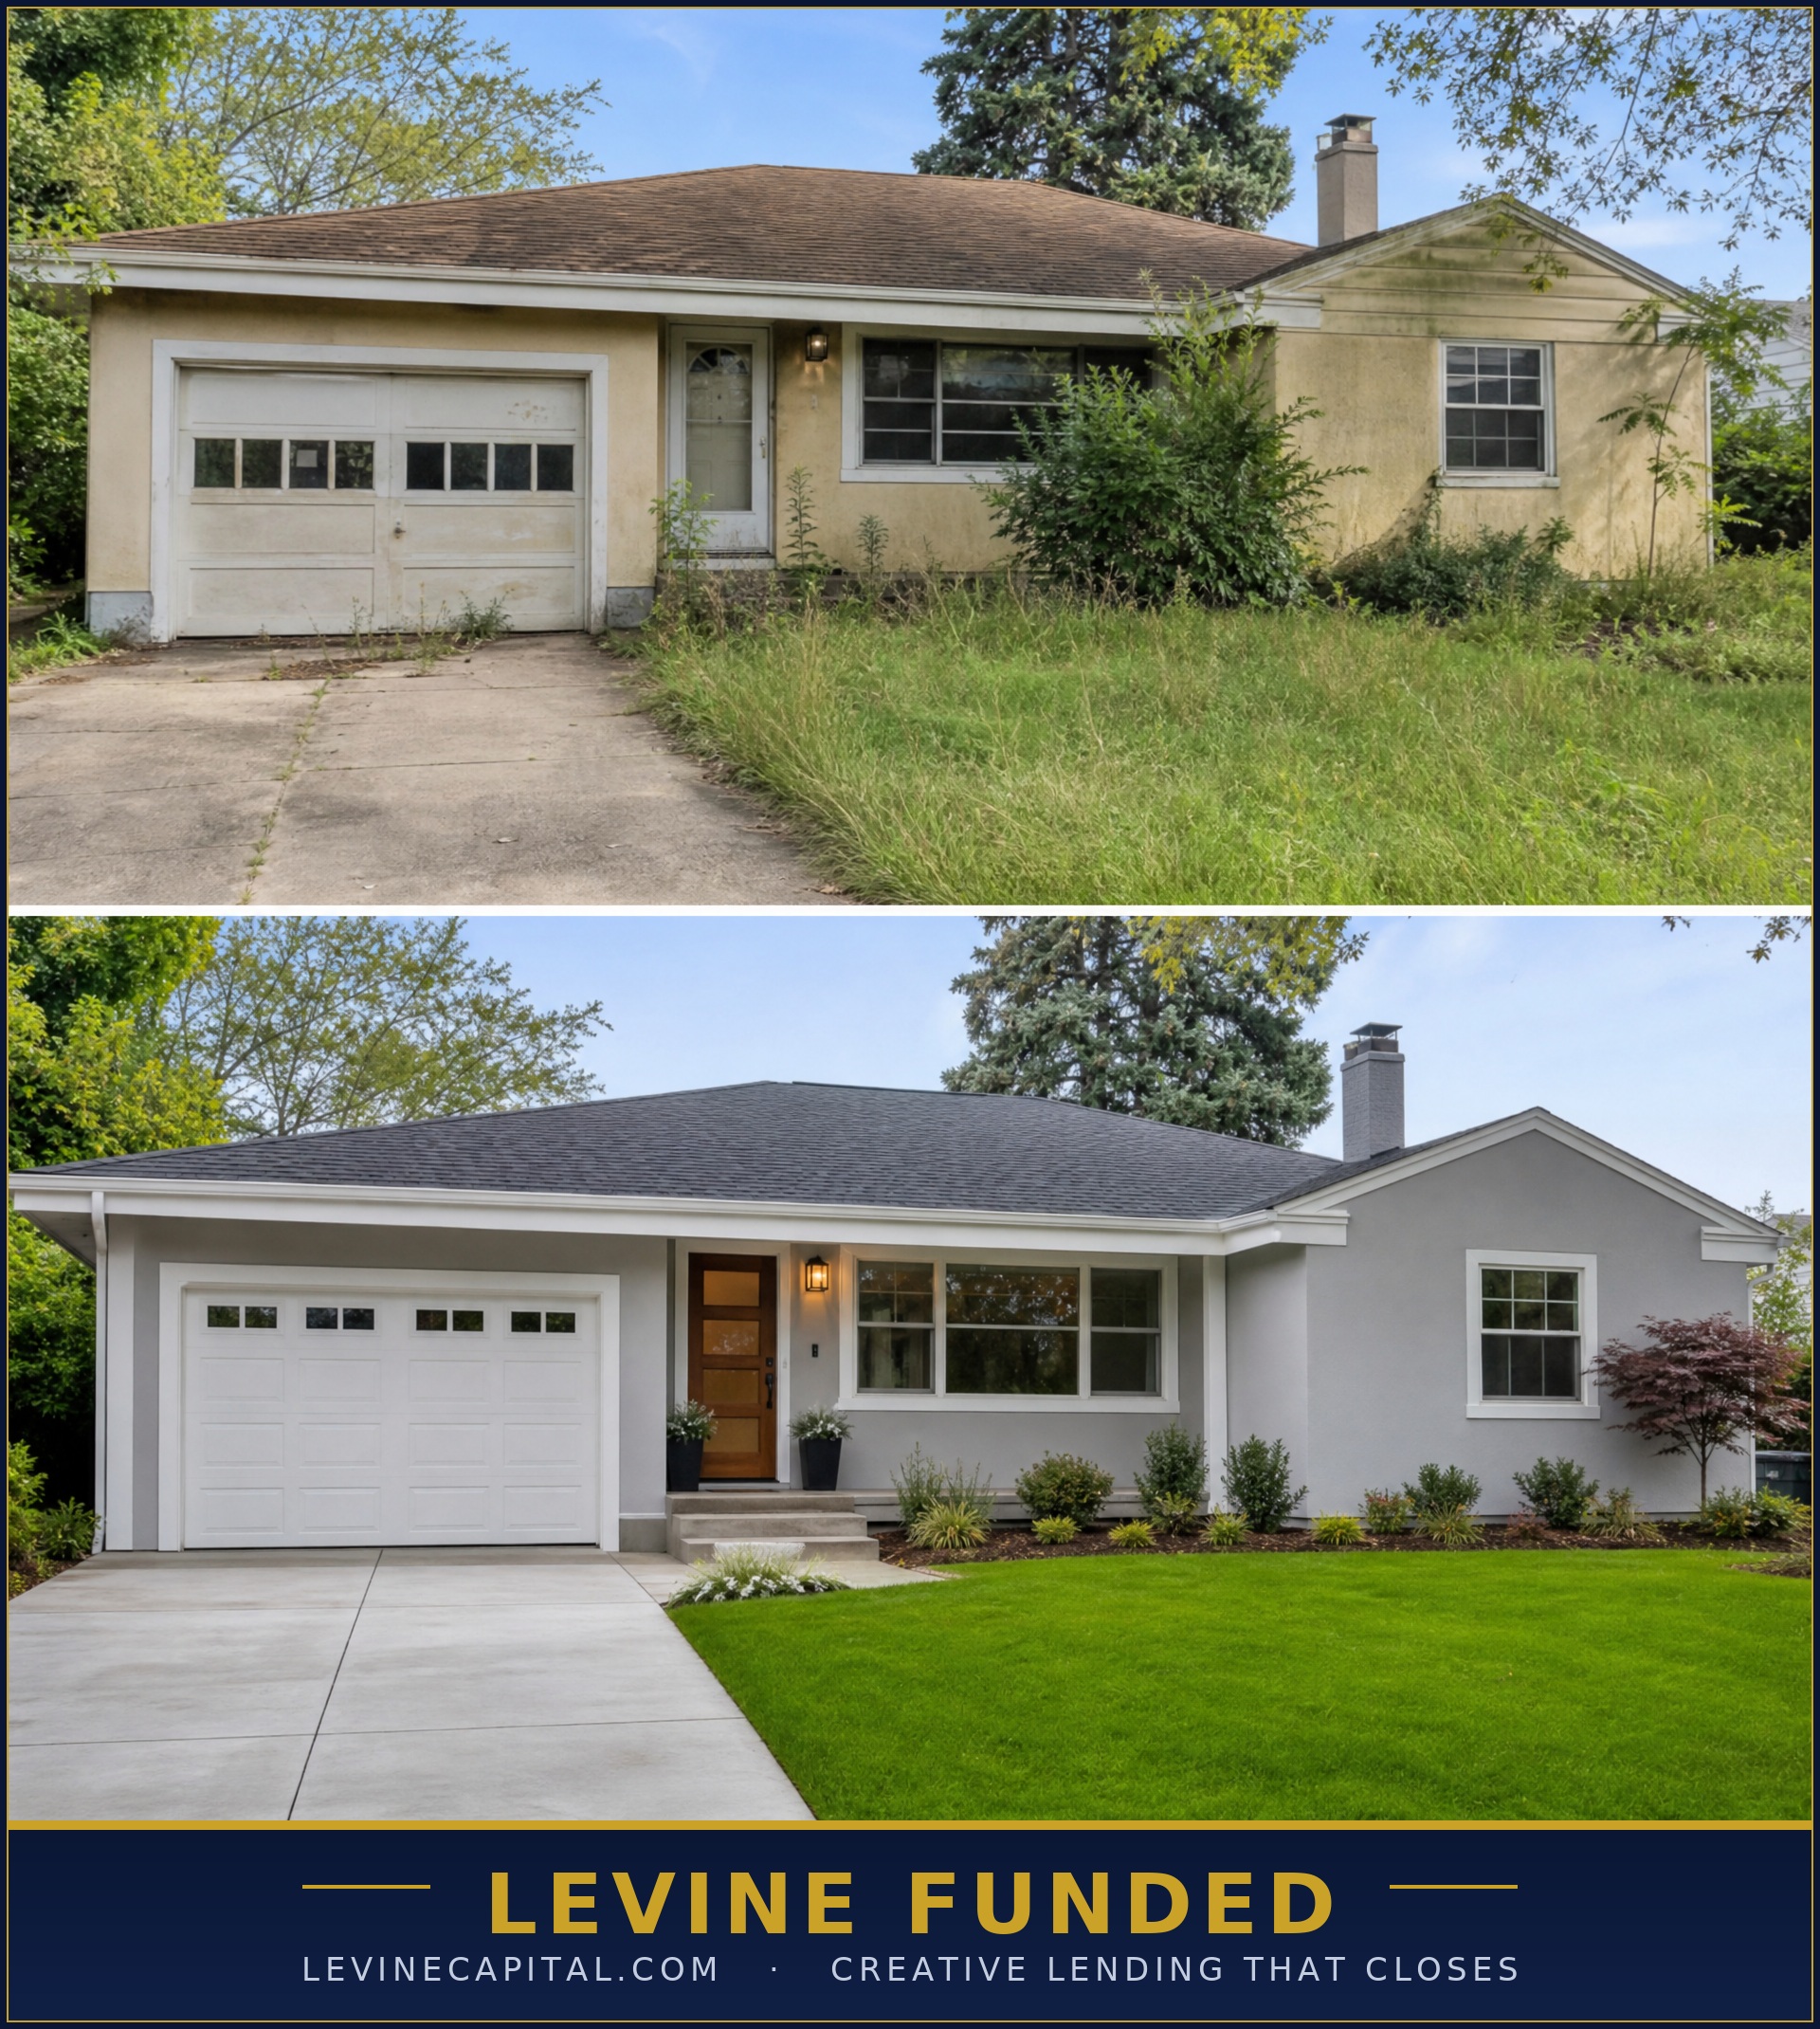
Levine Capital recently worked on a loan in which the borrower’s credit score had declined before the planned refinance. The original lending path no longer matched the borrower’s updated profile, even though the investor still needed a viable exit.
Rather than treating the first decline as the final answer, the Levine Capital team reviewed the revised credit profile and property-level facts, then pivoted the loan to a different capital provider whose program was better aligned with the scenario. The replacement structure worked, and the loan closed.
The important lesson is not that every low-credit loan will close. It is that one capital provider’s guidelines do not represent the entire market. Levine Capital maintains a diversified network of capital-provider, correspondent, and wholesale relationships, allowing the team to compare potential structures and seek the appropriate combination of pricing, leverage, and program fit for each qualified transaction.
Not every loan belongs in the same program. The goal is to identify the capital channel that best fits the borrower, property, and exit—not to force every investor into a single box.
How a Bridge-to-DSCR Rescue Strategy Can Work
For an investor with an unfinished project and damaged credit, the solution may require deliberate stages rather than one rushed refinance.
Stage 1: Rescue and completion
The objective is to replace the existing fix-and-flip lender and potentially fund remaining construction. The borrower generally must demonstrate an acceptable payoff, sufficient equity, a credible budget, a defined remaining scope of work, project viability, and a realistic exit.
Stage 2: Stabilization
The objective is to complete repairs, obtain required occupancy documentation, and establish eligible rent. The property generally needs to be finished and marketable, properly insured, supported by a lease or qualifying market rent, and compliant with program requirements.
Stage 3: Long-term refinance
The objective is to refinance into a DSCR rental loan. The borrower generally must demonstrate acceptable DSCR, appraisal, credit profile, reserves, entity and title structure, and complete underwriting approval.
This approach can give a qualified investor a brand-new financing plan and a clearer exit, but it must be based on verified numbers. The current payoff, remaining construction cost, as-completed value, expected rent, taxes, insurance, and total monthly payment all affect feasibility.
Who May Be a Fit?
A low-FICO DSCR or bailout refinance review may be appropriate for a real estate investor who owns or is acquiring a business-purpose investment property and faces one of the following situations:
- The credit score declined during a rehab because project costs increased revolving balances.
- A completed rental property is producing or can support qualifying rent, but the borrower no longer meets a conventional or higher-FICO program.
- A fix-and-flip loan is approaching maturity, has matured, or is in default.
- Construction is incomplete and the borrower needs to replace the current lender.
- The existing lender will provide a payoff but will not extend additional construction capital.
- A BRRRR investor needs a realistic refinance path before moving to the next property.
A review does not guarantee eligibility. Properties with insufficient equity, unsupported values, unworkable construction budgets, title problems, inadequate insurance, unresolved liens, or no credible exit may not qualify.
What Levine Capital Will Need to Review the Scenario
A complete submission helps the team identify the right capital channel quickly. Investors should be prepared to provide the property address, estimated credit score, current loan payoff, maturity or default status, purchase price, amount invested to date, renovation budget, remaining scope of work, current property condition, estimated after-repair value, expected market rent, and intended exit strategy.
For completed or nearly stabilized rentals, the team may also request a lease, proof of rent, insurance information, entity documents, bank statements or reserve verification, and access for an appraisal. For unfinished projects, photographs, contractor information, invoices, permits, and a detailed remaining budget may be required.
Why Work With Levine Capital?
Levine Capital does not rely on a single lending box. The company uses tailored institutional correspondent and wholesale capital, together with a diversified capital-provider network, to evaluate investor scenarios across multiple possible programs.
That flexibility matters when a deal changes midstream. A lower credit score, a delayed renovation, or a maturing bridge loan may require a different provider and a different structure than the investor originally expected. Levine Capital’s role is to understand the complete transaction, identify realistic financing paths, and present the scenario to the capital source positioned to evaluate it.
No lender can make every deal work. But investors deserve more than an automatic decline when a property has value, the business plan remains viable, and a responsible exit can be documented.
Frequently Asked Questions
Can I get a DSCR loan with a 550 credit score?
Levine Capital can evaluate a DSCR program with a minimum FICO score as low as 550 for eligible business-purpose investment properties. Approval and terms depend on the property’s qualifying cash flow, appraisal, loan purpose, leverage, reserves, borrower history, documentation, location, and the applicable capital provider’s current guidelines.
Can a DSCR loan refinance an unfinished renovation?
Usually, an unfinished property first requires a bridge, mid-construction, or construction-completion refinance. Once the project is complete and the property is rent-ready or stabilized, the investor may be able to pursue a DSCR refinance, subject to all program and underwriting requirements.
Can Levine Capital refinance a fix-and-flip loan that is already in default?
Potentially. A default does not automatically prevent a refinance, but time, equity, payoff terms, property condition, remaining construction costs, and the credibility of the exit plan are critical. Levine Capital must review the complete scenario before determining whether an available capital provider may consider it.
Can the new loan include money to finish construction?
In some eligible transactions, a new bridge or completion loan may include funds for approved remaining work. The amount and disbursement structure depend on the current value, projected value, existing payoff, borrower equity, construction budget, inspections, and underwriting.
What if my credit fell because I used personal cards for the rehab?
That is a common scenario Levine Capital can evaluate. The team will review the current credit profile together with the property’s value, rent potential, reserves, and overall transaction. A lower-FICO DSCR option may be available if the property is ready for long-term rental financing; otherwise, a bridge-to-DSCR strategy may be more appropriate.
Does a 550 credit score guarantee approval?
No. A minimum credit score identifies the lowest score a particular program may consider; it is not a promise of approval. Final eligibility and terms are determined after complete underwriting and may change based on the entire loan file.
Get a Fresh Review Before Giving Up on the Deal
If your credit score dropped during a BRRRR renovation, your fix-and-flip loan is maturing, your current lender will not extend, or your project needs additional funds to reach completion, do not assume the original decline is the end of the road.
Levine Capital can review the payoff, construction status, property value, expected rent, credit profile, and exit strategy to determine whether a low-FICO DSCR loan, mid-construction bailout refinance, or bridge-to-DSCR plan may fit.
Submit Levine Capital’s Quick Quote in less than five minutes to request a financing review.
Potential financing is subject to entity review, underwriting, appraisal, title, insurance, capital-provider guidelines, and written approval.
Important disclosure: This article is for general informational and marketing purposes only and is not a commitment to lend or a guarantee of approval, pricing, leverage, proceeds, construction funding, or closing. Programs and guidelines are subject to change without notice. A minimum FICO score of 550 may be considered only for certain eligible scenarios and does not apply to every property, borrower, loan purpose, or jurisdiction. All financing is for qualifying business-purpose investment transactions and is subject to complete underwriting and written terms.